"Mortgage-free" is a bold phrase, so let us define it carefully. We are not suggesting that a mortgage disappears. We are describing a strategy in which rental income from a second home covers a large share, and in some scenarios most or all, of your monthly housing payment. The practice is often called house hacking, and a dual-residence property is one of the cleanest ways to do it.
The Core Idea
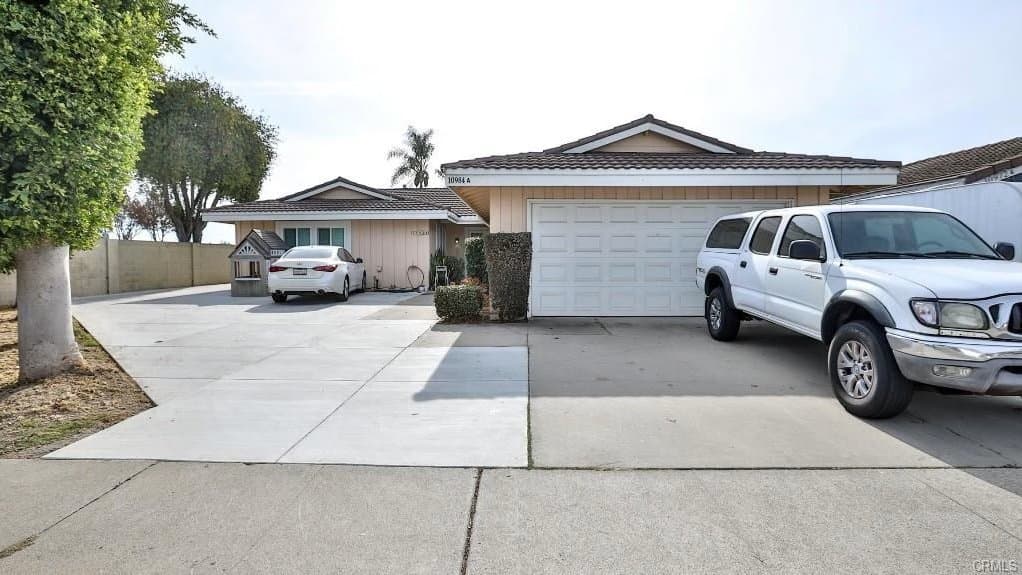
At 10984 Goldeneye Ave in Fountain Valley, the 1,200 sq. ft., 3 bed / 2 bath ADU has an income potential of $3,500 per month. You live in the remodeled 1,716 sq. ft. main home, and the ADU tenant's rent works toward your mortgage, taxes, and insurance.
Because the ADU is a full second residence with a separate address and separate meters, it can function as a stand-alone rental while you enjoy your own privacy.
A Simple Offset Framework
Here is a worksheet you can adapt with your own figures:
- Estimate your total monthly housing cost. Include principal, interest, property taxes, insurance, and a maintenance reserve.
- Estimate net rental income. Start with $3,500, then subtract vacancy and any costs you pay as landlord.
- Subtract the net rent from your housing cost. The result is your effective monthly cost.
- Stress test it. What happens if rent is lower or the unit is vacant for two months?
This exercise changes the way buyers think. Instead of asking, "Can I afford this payment?" you ask, "What is my payment after the property helps pay for itself?"
Why Separate Meters and Solar Help
Two features strengthen the offset story:
- Separate meters let you pass utility costs to the tenant, which protects your net income.
- Paid solar on the ADU means there is no solar lease payment, and it can reduce electricity expenses.
These details do not make headlines, but they preserve more of each rent dollar.
What Lenders May Consider
Some lenders consider rental income from an ADU when qualifying a borrower, which can expand purchasing power. Rules vary significantly by loan program, down payment, and documentation, so speak with a qualified lender early. We will cover this topic in depth in a later article.
Common Mistakes to Avoid
- Counting 100 percent of rent as profit. Always subtract vacancy and expenses.
- Ignoring reserves. Keep cash available for repairs and turnover.
- Skipping the lease details. A clear lease protects both sides.
- Underestimating taxes. Rental income has tax consequences, so consult a professional.
Who Benefits Most
This strategy is especially attractive for:
- Move-up buyers who want a larger home but worry about the payment.
- First-time buyers with a long-term mindset who are comfortable with a tenant on the lot.
- Savvy homeowners who see their home as an asset that should work for them.
The Lifestyle Side
A financial plan only works if you enjoy living with it. A separate address and private entry for the ADU, plus a corner lot with space between structures, help maintain the feeling that you are living in your own home rather than managing a boarding house.
Beyond the Mortgage
Once the loan is paid down, or if rents rise, your cash flow improves further. The ADU can also be repurposed for family later, so the same home that offsets your payment today can house a parent or adult child tomorrow.
Get Your Numbers
Every buyer has a different down payment, interest rate, and tolerance for risk, so a one-size-fits-all number is not helpful. That is why we offer a custom mortgage offset calculator tailored to 10984 Goldeneye Ave.
Request your Custom Mortgage Offset Calculator and see how ADU income could change your monthly cost of ownership.
Disclosure: This article is for general information and is not financial, tax, or legal advice. Rental income is not guaranteed. Consult licensed professionals before making decisions.